
Market Insights
US CPI: the key market event of the week
Wednesday's US inflation report could set the direction for the dollar, Treasury yields, gold and equities. A hotter reading would lift yields and the dollar, while a softer one would ease financial conditions and support stocks and gold.
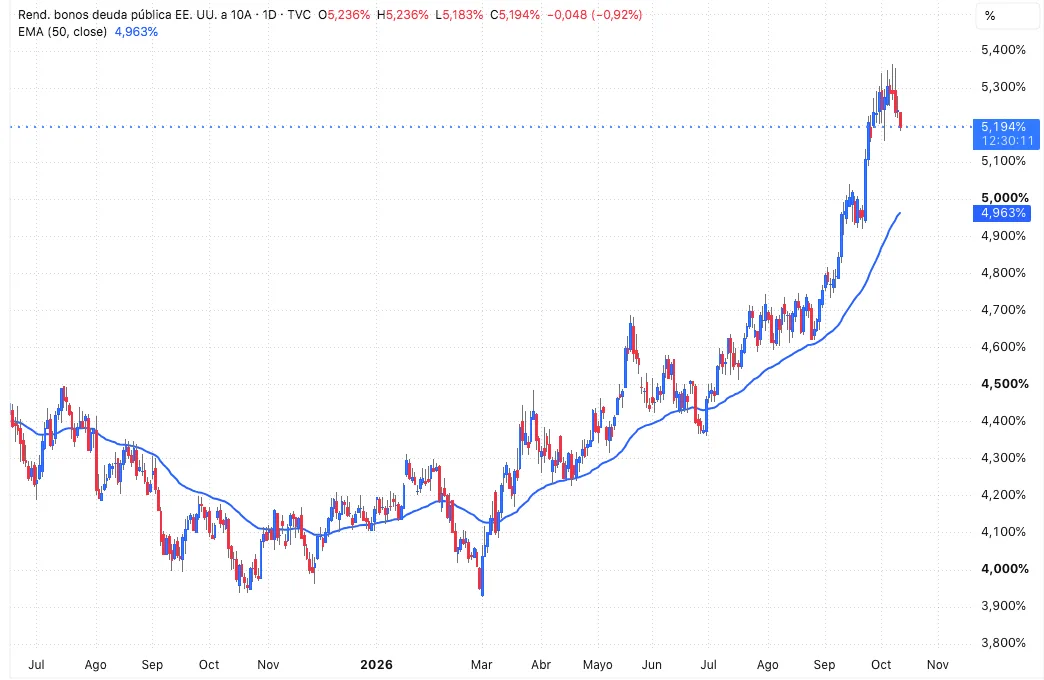
Financial markets face a week in which the US inflation data could determine the direction of the US dollar, Treasury yields, gold and equities. Following the sell-off late last week amid concerns about the profitability of investments in artificial intelligence, US stocks managed to recover, with broad-based gains led by the Dow Jones. However, the rebound has not dispelled concerns about the high valuations of some technology companies, their ability to generate returns from AI investments, and the impact that persistently high financing costs could have on economic activity.
Against this backdrop, the release of the US Consumer Price Index (CPI), scheduled for Wednesday, takes on particular importance. Expectations point to an acceleration in headline inflation, while the monthly core inflation rate, which excludes food and energy, is expected to moderate. This divergence will make the details of the report particularly important, as markets assess price trends beyond the more volatile components. If the increase is mainly driven by energy prices, its impact could be more limited. However, if inflationary pressures spread across other categories, doubts will grow over the Federal Reserve’s ability to ease monetary policy in the coming months.
The bond market will probably be the main barometer of the market reaction. Recent movements in US Treasury yields reflect investors’ sensitivity to inflation expectations, the outlook for interest rates and geopolitical risks. A higher-than-expected CPI reading, particularly if core inflation also surprises to the upside, could trigger another rise in Treasury yields by reinforcing expectations that the Fed will have to keep interest rates elevated for longer. This scenario would support the US dollar and put additional pressure on equities, especially technology stocks, whose valuations are particularly sensitive to financing costs and future growth expectations. Conversely, softer inflation could ease pressure on yields, weaken the dollar and provide some support for stocks.
Gold will also be influenced by this combination of monetary and geopolitical factors. The precious metal rallied sharply late last week after Donald Trump ruled out attacks on Iran before the November elections and said that productive talks had taken place. The news coincided with a decline in US Treasury yields and the dollar, two developments that tend to support gold by reducing the opportunity cost of holding a non-interest-bearing asset. Nevertheless, market sentiment remains vulnerable to changes in interest rate expectations and developments in negotiations between Washington and Tehran.
Geopolitical tensions remain unresolved. Over the weekend, Iran described the US response to its proposal to restore shipping through the Strait of Hormuz as insufficient, noting that several issues remained outstanding. Negotiations are continuing, but the risk of renewed tensions keeps oil markets on alert. A significant rise in crude prices could reignite inflationary pressures and complicate the Federal Reserve’s decisions, while also increasing energy costs for businesses and consumers. Oil prices therefore remain an additional factor that could influence both the interpretation of the CPI report and the market reaction.
These uncertainties are compounded by less encouraging signals from the US economy. Consumer confidence fell short of expectations, while inflation expectations edged higher, raising questions about the resilience of consumer spending in an environment of restrictive financial conditions. Investors will need to assess whether the inflation data confirms that price pressures remain persistent or, alternatively, provides room for future monetary easing without a significant deterioration in economic activity.
Ultimately, the US CPI will be the week’s key market event, as it could determine whether the recent decline in Treasury yields continues or gives way to another upward move. An upside surprise could strengthen the dollar, weigh on equities and limit gold’s upside potential, particularly if accompanied by rising oil prices. A softer reading, by contrast, could push yields lower and ease financial conditions, supporting both risk assets and precious metals. In a market balancing growth expectations, inflation and geopolitical tensions, the reaction in US Treasuries will be a crucial signal for anticipating the next market moves.
Original analysis by Miguel A. Rodriguez, dated 13 October 2026.
This commentary is general market information, not investment advice. It does not take your objectives or financial situation into account, and past performance does not guarantee future results. Trading CFDs involves a significant risk of loss.